I hope you enjoy reading this blog post. If you want to book a free consultation, click here.
Gold has always been a safe haven for Indian investors looking. But buying physical gold or standard gold ETFs comes with a straightforward risk: if the market price drops, your portfolio value drops with it.
What if there was a way to magnify your returns if gold goes up, while providing a protection to your capital if the prices fall?
That is exactly what the Alpha Gold Edge 3.5 Years, a structured product distributed by Nuvama Wealth and issued by Alpha Alternatives, aims to do. In this review, we are breaking down exactly how this Principal Protected Market Linked Debenture (PP-MLD) works, the math behind the returns and the crucial trade-offs you need to know before investing.
Product Overview: The Basics
Before we look at the return scenarios, here are the core specifications of the instrument:
- Instrument Type: Principal Protected Market Linked Debenture (PP-MLD)
- Underlying Asset: MCX Gold
- Tenure: 3.5 Years
- Issuer: Alpha Alternatives Financial Services Private Limited
- Credit Rating: CARE PP MLD A- (Stable) / ACUITE PP-MLD A (Stable). This indicates an adequate degree of safety regarding the timely servicing of financial obligations.
How Alpha Gold Edge Works: The 2 Core Features
This structure is designed around two specific mechanisms that alter how you experience gold’s market movements:
1. Enhanced Participation (The Upside Multiplier)
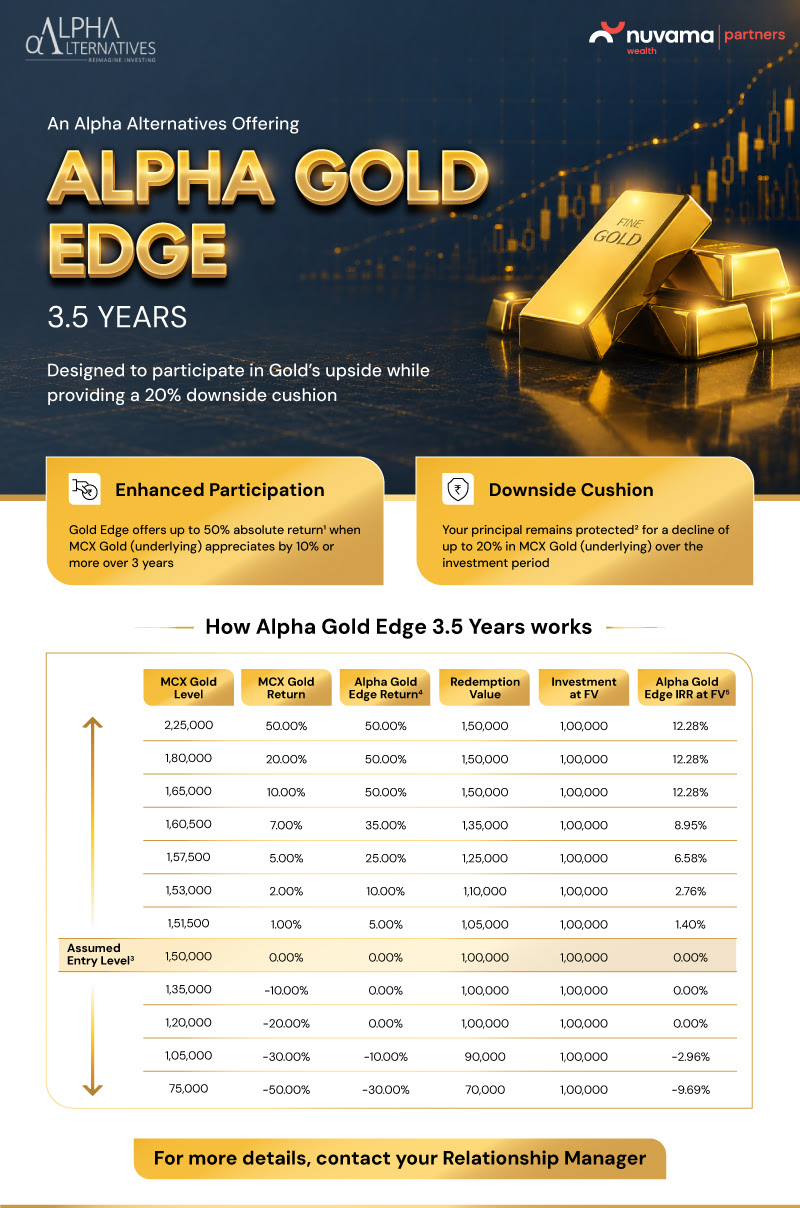
Instead of a 1:1 return, this product offers a multiplier effect on moderate gains. If MCX Gold appreciates by 10% or more over the 3.5-year tenure, the product is engineered to deliver a maximum absolute return of 50% (which translates to an IRR of roughly 12.28%).
2. Downside Cushion (The Capital Protection)
To protect against market volatility, the product features a 20% safety net. If the price of MCX Gold declines by up to 20% by maturity, your principal investment remains 100% protected.
The Math: 4 Real-World Scenarios
To understand how this actually plays out, let’s look at how a hypothetical investment of ₹1,00,000 performs under different market conditions at the end of the 3.5 years.
| Market Scenario | MCX Gold Return | Your Absolute Return | Final Value |
| The “Bull Run” | +20% to +50% | +50.00% (Capped) | ₹ 1,50,000 |
| The “Mild Bull” | +5.00% | +25.00% (5x Multiplier) | ₹ 1,25,000 |
| The “Mild Bear” | -10.00% to -20.00% | 0.00% (Principal Protected) | ₹ 1,00,000 |
| The “Crash” | -30.00% | -10.00% (Cushion absorbs first 20%) | ₹ 90,000 |
The Trade-Offs: What You Need to Know
To get that downside cushion and the upside multiplier, you are making two specific trade-offs:
- Your Upside is Capped: Your maximum return is hard-capped at 50% absolute. If gold enters a massive super-cycle and surges by 70% over the next three years, standard physical gold would yield 70%, but this MLD will only yield 50%.
- Downside Protection has Limits: The structure protects your capital against a moderate drop (up to 20%). If gold crashes severely (e.g., a 40% drop), you will take a loss, though it will be buffered by 20% (resulting in a 20% loss to your capital).
Important Investment Details
If you are considering adding this to your debt or alternative portfolio, keep these operational details in mind:
- Minimum Investment: The base Face Value (FV) of one unit is ₹1,00,000. (Note: Wealth platforms like Nuvama may set higher minimum ticket sizes for participation, often starting at ₹10 Lakhs).
- Format: The investment is issued in a dematerialized form, meaning you must have an active Demat account to hold the debentures.
- Taxation: As per recent changes to the Finance Bill, returns on Market Linked Debentures (MLDs) are now classified as Short-Term Capital Gains (STCG). Regardless of the 3.5-year holding period, the gains will be taxed at your applicable marginal income tax slab rate.
- How to Invest: Because this is a privately placed structured product, it cannot be bought directly on public brokerage apps. It requires signing a term sheet and executing the transaction through your Nuvama Relationship Manager or wealth partner.
The Bottom Line: Who is this for?
The Alpha Gold Edge 3.5 Years is not for the ultra-aggressive investor expecting gold prices to double. Instead, it is a highly tactical allocation for the moderately bullish investor.
If you believe gold will rise slightly or remain range-bound over the next three years, this structure allows you to lock in a 5x multiplier on the upside while resting easy knowing your capital has a firm 20% safety net beneath it.
Share This Story, Choose Your Platform!
About the Author: Donald Gonsalves